降低结果的标准差
或者
提高结果的期望值? → 套期保值降低的是方差/风险,并不承诺更高的期望收益!
Reduce the standard deviation of the outcome
OR
Increase the expected value of the outcome? → Hedging reduces variance/risk; it does not promise higher expected returns!
学习目标
- 探讨空头与多头套期保值策略 (Long and Short Hedges)
- 界定基差风险 (Basis Risk):
- 探讨影响基差风险的核心因素
- 基差风险如何影响套期保值的有效性与最终成果?
- 计算并深入解读最小方差套期保值比率 (
- 确定套期保值中的最优合约数量 (
- 利用股指期货实现:
- 对冲股票投资组合的市场系统性风险
- 灵活调整股票组合的 Beta 系数
- 阐述如何实施“远期滚动对冲” (Stack-and-Roll / 展期对冲)
Learning Objectives
- Discuss long and short hedges
- Define basis risk:
- Discuss the factors affecting basis risk
- How does basis risk affect hedging profitability?
- Calculate and interpret the minimum variance hedge ratio (
- Determine the optimal number of contracts in a hedge (
- Use index futures to:
- Hedge a stock portfolio
- Change the beta of a stock portfolio
- Explain how to “roll the hedge forward” (stack-and-roll)
风险敞口
- 资产多头风险敞口 (Long Asset Exposure):
- 已经拥有现货资产,或已签订协议将在未来生产该资产。
- 计划在未来特定时间将其出售。
- 面临风险: 资产价格下跌风险 → 对冲策略:建立期货空头头寸 (Short Futures)。
- 示例:金矿公司。
- 资产空头风险敞口 (Short Asset Exposure):
- 在未来某一时间需要采购该资产。
- 面临风险: 资产价格上涨风险 → 对冲策略:建立期货多头头寸 (Long Futures)。
- 示例:珠宝商。
- 套期保值的基本原则:建立一个能够抵消(中和)风险的头寸。
Risk Exposure
- Long Asset Exposure:
- Already own the asset or have contracted to produce it.
- Wish to sell it in the future.
- Risk: Asset price falls → hedge by taking a Short Futures position.
- Example: a gold mining company.
- Short Asset Exposure:
- Need to purchase the asset in the future.
- Risk: Asset price rises → hedge by taking a Long Futures position.
- Example: a jeweler.
- Basic principle of hedging: take a position that neutralises the risk.
套期保值中的基差
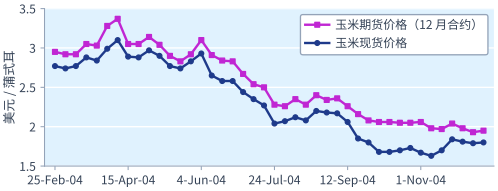
- 在套期保值中,基差 (Basis) 是被对冲资产的现货价格
- 基差可正(当
- 若被对冲的资产与期货合约的基础资产完全一致,则在合约到期时刻
The Basis in a Hedging Situation
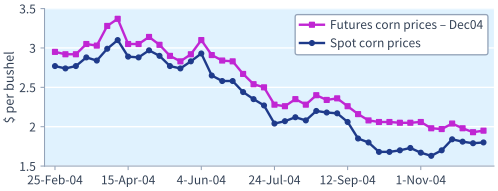
- In a hedging situation the basis is the difference between the spot price
- Basis can be positive (when
- If the asset being hedged and the asset underlying the futures contract are identical, then at contract maturity
空头套期保值
- 空头套期保值 (Short Hedge) 是指在期货市场上建立期货空头(卖出)头寸。
- 适用于套期保值者已经拥有某种资产、并预计在未来某个日期将其出售的情形。
- 或者适用于当前尚未拥有该资产、但在未来将生产并销售该资产的企业。
- 价格下跌的风险:价格下跌时,期货空头头寸获利。
- 降低不确定性的方式:
- 用期货市场的盈利抵消现货市场的亏损(若现货价格上涨,现货出售端的收益则被期货空头的亏损抵消);
- 锁定价格。
- 空头套期保值无法保留价格朝有利方向变动时的收益。
Short Hedge
- A short hedge involves taking a short position in a futures contract.
- It is appropriate when the hedger already owns an asset and expects to sell it at some future date.
- Alternatively, it is appropriate when an asset is not currently owned but will be produced and sold in the future.
- Risk of a price decrease: the short futures position benefits when the price falls.
- Reduce uncertainty by:
- offsetting losses in the physical market with gains in the futures market (if the spot price rises, the gain on the spot sale is offset by the loss on the short futures position);
- locking in the price.
- A short hedge cannot preserve the benefits from favourable price movements.
案例分析 – 空头套期保值 (玉米生产商)
- 3 月份:农场主预计将在 9 月份出售玉米。
- 当 12 月合约的期货价格为
- 当 12 月合约的期货价格为
- 为什么不使用 9 月份的期货合约?
- 9 月份:农场主准备在现货市场上以
- 当 12 月合约的期货价格为
- 当 12 月合约的期货价格为
Example – Short Hedge (Corn Producer)
- March: the farmer expects to sell corn in September.
- Hedges by entering into a short December futures position when the futures price for December contracts is
- Hedges by entering into a short December futures position when the futures price for December contracts is
- Why is the September futures contract NOT used?
- September: the farmer is ready to sell corn in the physical (spot) market at
- Closes out the futures position by entering a long December futures position when the futures price for December contracts is
- Closes out the futures position by entering a long December futures position when the futures price for December contracts is
空头套期保值与基差
- 假定某空头对冲策略在时刻
- 实际收到的价格:现货价格
- 若基差为 0(
- 若基差
- 若基差意外走强(
Short Hedge and Basis
- Suppose a short hedge is initiated at time
- Effective price received: the spot price
- If the basis is 0 (
- If the basis
- The short hedger's position improves if the basis strengthens unexpectedly (
多头套期保值
- 多头套期保值 (Long Hedge) 适用于套期保值者将在未来买入某种资产、并希望提前锁定采购价格的情形。
- 价格上涨的风险:通过建立期货多头头寸来对冲该风险;价格上涨时期货多头获利。
- 在
- 在
- 案例分析: 某电气制造厂商已知 5 月份需要采购 100,000 磅铜。1 月份时,5 月到期铜期货价格为 $3.20/磅。
- 该制造商买入 4 张 5 月铜期货合约(每张 25,000 磅)。
- 5 月份时,在现货市场上以价格
Long Hedge
- A long hedge is appropriate when the hedger will purchase the asset in the future and wants to lock in the purchase price.
- Risk of a price increase: hedge this risk by entering into a long position in futures, which benefits when the price rises.
- At
- At
- Example: An electrical manufacturer knows it will need 100,000 lbs of copper in May. In January, May copper futures trade at $3.20/lb.
- Manufacturer buys 4 May copper futures contracts (25,000 lbs each).
- In May, buys copper in the physical spot market at
多头套期保值与基差
- 实际支付的价格:支付的现货价格
- 若基差为 0(
- 若基差
- 若基差意外走弱(
Long Hedge and Basis
- Effective price paid: the spot price paid
- If the basis is 0 (
- If the basis
- The long hedger's position improves if the basis weakens unexpectedly (
套保者平衡:商业诉求与基差结构分解
现货生产商(农户) vs 现货采购商(麦片企业):
- 玉米种植户(空头套保者): 秋收时供给集中爆发。当地天量供给压低现货价格。提前做空期货以锁定生存保障收益;若现货崩盘,期货利润足以弥补。
- 麦片制造企业(多头套保者): 鉴于昂贵仓储成本,无法提前储存一整年用粮。通过做多期货锁定原料成本预算,防范农产品价格通胀冲击。
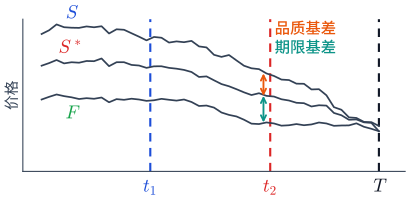
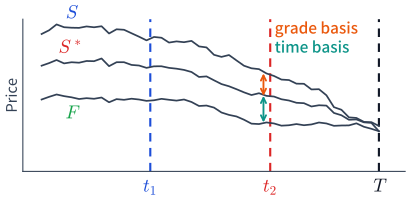
基差风险的分解(品质基差与期限基差):
Hedger Balance: Commercial Objectives & Basis Decomposition
Producer (Farmer) vs Consumer (Cereal Maker):
- Corn Farmer (Short Hedger): Harvests all supply at once. Massive local supply depresses harvest prices. Sells futures early to guarantee survival revenue. If spot collapses, futures gain compensates.
- Cereal Company (Long Hedger): Cannot store a full year's grain upfront due to storage costs. Longs futures to lock in raw ingredient budget and protect consumers from food price inflation.
Decomposition of basis risk (grade basis and time basis):
基差风险
- 套期保值策略能够极大地降低风险,但在现实中极少能够实现完全消除风险。这一残存的风险就是基差风险 (Basis Risk)。
- 基差风险源于平仓时基差
- 实际中的成因:
- 套期保值者可能无法确定买入或卖出资产的具体日期。
- 对冲可能需要在期货合约到期日
- 需要对冲价格的资产与期货合约的基础资产并不完全相同(交叉对冲 Cross-Hedging)。
- 地点错配:合约规定的交割地点与现货所在地不同。
- 这些问题造成基差风险:
- 基差风险是商品期货的普遍问题,但在金融期货中同样可能出现,例如公司用股指期货对冲自己的股票组合。
Basis Risk
- Hedging strategies minimize risk, but in practice rarely eliminate it completely. This remaining risk is basis risk.
- Causes in practice:
- The hedger may be uncertain about the exact date when the asset will be bought or sold.
- The hedge may require the futures contract to be closed out well before its maturity
- The asset whose price is to be hedged is not exactly the same as the asset underlying the futures contract (cross hedging).
- Location mismatch: delivery is specified at a different geographical point.
- These problems create basis risk:
- Basis risk arises from the uncertainty about the basis
- Basis risk is a generic problem with commodities, but it can also arise with financial futures, for example when a company hedges its own portfolio with index futures.
- Basis risk arises from the uncertainty about the basis
最小化基差风险 – 合约选择准则
- 关键在于期货合约的选择:
- 交割月份:选择交割月份尽可能接近、但晚于套期保值结束日期的合约。尽量避免将期货持有至交割月份:进入交割月后交易流动性往往枯竭,且交割物流会造成价格异常波动。
- 基础资产:当被对冲资产没有对应的期货合约时,选择其期货价格与该资产价格相关性最高的合约。
- 当被对冲资产(图中
Minimizing Basis Risk – Contract Choice
- A key factor is the choice of the futures contract:
- Delivery month: choose a delivery month that is as close as possible to, but later than, the end of the life of the hedge. Avoid holding futures into the actual delivery month: trading can become illiquid and erratic price spikes occur due to delivery logistics.
- Underlying asset: when there is no futures contract on the asset being hedged, choose the instrument whose futures price is most highly correlated with the asset price.
- When the asset to be hedged (
最小方差套期保值比率
- 若期货合约的基础资产与被对冲资产相同,期货头寸的规模应与风险敞口的规模相同。
- 但这未必能使风险最小。
- 最优的套期保值比率应使头寸的方差最小。
- 套期保值比率 (Hedge Ratio)
- 为使被对冲组合资产价值的方差最小化:
- 公式参数说明:
Minimum Variance Hedge Ratio
- If the asset underlying the futures contract is the same as the asset being hedged, the size of the futures position should be the same as the size of the exposure.
- This may not necessarily minimize risk.
- The optimal hedge ratio should minimize the variance of the position.
- The hedge ratio
- To minimize the variance of the hedged position value:
- where:
最优对冲合约数量
- 变量设定:
- 最优合约数量计算公式:
- 在实际操作中,所用合约的数量必须是整数,因此只能近似地实现最优对冲。
- 若考虑每日逐日盯市结算的利率再投资效应(尾随对冲 Tailing the Hedge):
Optimal Number of Contracts
- Let:
- Optimal Number of Contracts Formula:
- In practice the number of contracts used must be an integer, therefore only an approximation to the optimal hedge is possible.
- If daily settlement (tailing the hedge) is taken into account:
案例分析 – 最优合约数量 (活牛/牛肉)
- 某农场主利用期货对冲 18,000 千克 牛肉的销售。每张期货合约的交割规模为 1,500 千克。
- 套期保值比率:
做空的期货合约价值应为被对冲头寸价值的 120%。
- 因此应做空:
Example – Optimal Number of Contracts (Beef)
- A farmer hedges the sale of 18,000 kg of beef using futures. Each contract is for the delivery of 1,500 kg.
- Hedge ratio:
The futures contracts to be shorted should have 120% of the value of the position being hedged.
- Thus short:
交叉对冲规模测算与尾随调整
跨品种对冲案例(航油与取暖油期货):
某航空公司需采购 2,000,000 加仑航空煤油 (
已知统计参数:
尾随对冲调整 (Tailing the Hedge): 由于期货每日结算而非到期一次性结算,每日现金流可按短期利率
Cross-Hedge Sizing & Tailing Adjustments
Classic Problem (Airline Jet Fuel hedged with Heating Oil Futures):
Airline needs 2,000,000 gallons of jet fuel (
Tailing the Hedge (Daily Settlement Impact): Because futures are settled every day rather than at maturity, gains/losses can be reinvested at interest rate
利用股指期货对冲股票投资组合
- 非系统性风险(个股特有风险)可以通过构建充分多元化的投资组合加以分散消除。
- 系统性风险(大盘市场风险)无法通过分散化投资消除,但可以借助股票指数期货完美对冲!
- 资本资产定价模型 (CAPM) 将组合收益率
- 若股票组合与指数完全一致,最优套期保值比率为 1.0。
- 若组合并不与指数一致,则最优套期保值比率的估计值是 CAPM 中该组合的 Beta。
- 为彻底消除市场系统性风险(将组合有效
Hedging an Equity Portfolio with Index Futures
- Unsystematic (firm-specific) risk is eliminated by diversification.
- Systematic (market) risk cannot be diversified away, but it can be hedged using stock index futures!
- The Capital Asset Pricing Model (CAPM) links the portfolio return
- If the equity portfolio is identical to the index, the optimal hedge ratio is 1.0.
- When the portfolio does not mirror the index, an estimate of the optimal hedge ratio is the portfolio beta from the CAPM.
- To eliminate market risk (reduce
标普500指数期货与 SFE SPI 200 指数期货合约规格
资料来源:cme.com 与 sfe.com.au
| CME 标普 500 期货 (S&P 500 Futures) | |
|---|---|
| 交易单位 | 250 美元乘以标准普尔 500 股票价格指数 |
| 点值说明 | 1 点 = 0.01 指数点 = 2.50 美元 |
| 合约上市 | 3 月季度循环中的 8 个月份:3 月、6 月、9 月、12 月。 |
| 行权价间隔 | 不适用 |
| 产品代码 | 清算代码 = SP;交易代码 = SP |
| 交易场所:场内交易 (Floor) | |
| 交易时间 | 上午 8:30–下午 3:15。月末(下午 3:15);最后交易日(下午 3:15) |
| 上市说明 | 价格限制比例在每个日历季度初计算。交易暂停与主要证券市场的交易暂停相协调。 |
| 行权价 | 不适用 |
| 涨跌幅限制 | 较前一常规交易时段 (RTH) 结算价分别下跌 5.0%、10.0%、15.0% 和 20.0% 时触发价格限制。见股票限价规则。 |
| 最小变动价位 | 普通合约:0.10 = 25.00 美元 日历价差:0.05 = 12.50 美元 |
| 交易场所:CME Globex® 电子平台 | |
| 交易时间 | 周一至周四 下午 5:00–次日上午 8:15 及 下午 3:30–4:30;每晚下午 4:30–5:00 停市;周日及假日 下午 5:00–次日上午 8:15。 |
| 上市说明 | 季度循环中的近月合约。 |
| 行权价 | 不适用 |
| 涨跌幅限制 | 较前一结算价上涨或下跌 5% 时触发价格限制。 |
| 最小变动价位 | 普通合约:0.10 = 25.00 美元 |
CME S&P 500 Index Futures and SFE SPI 200 Index Futures Specifications
Source: cme.com and sfe.com.au
| CME S&P 500 Futures | |
|---|---|
| Trade Unit | $250 times the Standard & Poor's 500 Stock Price Index |
| Point Descriptions | 1 point = .01 index points = $2.50 |
| Contract Listing | Eight months in the March quarterly cycle. Mar, Jun, Sep, Dec. |
| Strike Price Interval | N/A |
| Product Code | Clearing=SP; Ticker=SP |
| Trading Venue: Floor | |
| Hours | 8:30 a.m.-3:15 p.m. Month end (3:15 p.m.) LTD (3:15 p.m.) |
| Listed | The percentage price limits are calculated at the beginning of each calendar quarter. Trading halts are coordinated with trading halts in the primary securities markets. |
| Strike | N/A |
| Limits | Price Limits corresponding to a 5.0%, 10.0%, 15.0% and 20.0% decline below the Settlement Price of the preceding RTH session. See Equity limits. |
| Minimum Fluctuation | Regular: 0.10 = $25.00 Calendar Spread: 0.05 = $12.50 |
| Trading Venue: CME® Globex® | |
| Hours | Mon/Thurs 5:00 p.m.-8:15 a.m. & 3:30 p.m.-4:30 p.m.; Shutdown period from 4:30 p.m. to 5:00 p.m. nightly; Sun & Hol 5:00 p.m.-8:15 a.m. |
| Listed | The Lead month in the Quarterly cycle. |
| Strike | N/A |
| Limits | Price limit corresponding to a 5% INCREASE or DECREASE from the Prior Settlement Price. |
| Minimum Fluctuation | Regular: 0.10 = $25.00 |
SFE SPI 200 指数期货合约规格
资料来源:sfe.com.au(原第 16 页右半部分)。与所有主要股指期货一样,该合约采用现金结算:无法按指数权重交割整篮成分股。
| 合约单位 | 每个指数点价值 25 澳元(例如指数为 5,000 点时合约价值 125,000 澳元)。 |
| 合约月份 | 3 月/6 月/9 月/12 月,最远至六个季度月份之后,另加最远至两个非季度月份的连续月份。 |
| 商品代码 | AP |
| 上市日期 | 2000 年 5 月 2 日 |
| 最小价格变动 | 一个指数点(25 澳元) |
| 最后交易日 | 到期合约于结算月第三个星期四中午 12:00 停止所有交易;未到期合约按规定交易时间继续交易。 |
| 现金结算价 | 最后交易日标普/澳交所 200 指数的特别开盘报价 (Special Opening Quotation)。该报价取最后交易日各成分股在该指数中的首笔成交价计算,不论这些股票在当日何时首次成交;因此各成分股的首笔成交价可能出现在最后交易日澳交所开市至收市(含收市单一价格竞价)之间的任意时点。 若某成分股在最后交易日澳交所收市前未成交,则以该股票最近一次的成交价计算特别开盘报价。 |
| 交易时间 | 下午 5:10–次日上午 7:00 及 上午 9:50–下午 4:30(美国夏令时期间) 下午 5:10–次日上午 8:00 及 上午 9:50–下午 4:30(美国非夏令时期间) |
| 结算日 | 到期后第一个营业日,SFE Clearing 公布合约的最终结算价;到期后第二个营业日,SFE Clearing 按结算价结算现金流。 |
| 持仓限额 | 无 |
| 每日价格限制 | 无 |
| CFTC 批准 | 是 |
SFE SPI 200 Index Futures Specification
Source: sfe.com.au (second half of the original slide 16). Like all major stock index futures, the contract is cash-settled: one cannot deliver the whole index basket of shares in exact index proportions.
| Contract Unit | Valued at A$25 per index point (e.g. A$125,000 at 5,000 index points). |
| Contract Months | March/June/September/December up to six quarter months ahead and serial months up to two non-financial quarter months ahead. |
| Commodity Code | AP |
| Listing Date | 02/05/2000 |
| Minimum Price Movement | One index point (A$25) |
| Last Trading Day | All trading in expiring contracts ceases at 12.00pm on the Third Thursday of the settlement month. Non-expiring contracts will continue to trade as per the stated trading hours. |
| Cash Settlement Price | The Special Opening Quotation of the underlying S&P/ASX 200 Index on the Last Trading Day. The Special Opening Quotation is calculated using the first traded price of each component stock in the S&P/ASX 200 Index on the Last Trading Day, irrespective of when those stocks first trade in the ASX trading day. This means that the first traded price of each component stock may occur at any time between ASX market open and ASX market close (including the Closing Single Price Auction) on the Last Trading Day. Should any component stock not have traded by ASX market close on the Last Trading Day, the last traded price of that stock will be used to calculate the Special Opening Quotation. |
| Trading Hours | 5.10pm – 7.00am and 9.50am – 4.30pm (during US daylight saving time) 5.10pm – 8.00am and 9.50am – 4.30pm (during US non daylight saving time) |
| Settlement Day | The first business day after expiry, SFE Clearing publishes the final settlement price of the contract. On the second business day after expiry, SFE Clearing settles cash flows as a result of the settlement price. |
| Position Limit | None |
| Daily Price Limit | None |
| CFTC Approved | Yes |
案例分析 – 对冲股票投资组合
- 某投资者持有 5000 万美元 的股票组合,Beta 系数
- 使用 SFE SPI200 期货合约:
- 指数点位 = 5,500 • 标普/澳交所 200 指数股息率 = 每年 3% • 无风险利率 = 每年 6%
- 套期保值所需的期货合约数量为
- 套期保值者建立 287 张 6 个月期标普/澳交所 200 指数期货的空头头寸。
- 如果 4 个月后,指数为 5,200、期货价格为 5,226 时对冲平仓,结果会怎样?
Example – Hedging an Equity Portfolio
- An investor holds a $50 million portfolio with beta
- Use the SFE SPI200 futures contract:
- Index level = 5,500 • dividend yield on the S&P/ASX200 index = 3% p.a. • risk-free rate = 6% p.a.
- The number of futures contracts required for hedging is
- The hedger enters into a SHORT position in 287 6-month S&P/ASX200 index futures contracts.
- What will happen if in 4 months the hedge is closed out when the index is 5,200 and the futures price is 5,226?
案例分析 – 对冲股票投资组合
4 个月后:
- 期货空头平仓的盈利:
- 股票组合的预期损失:
- 指数跌幅
- 指数 4 个月的股息
- 指数收益率
- 4 个月的无风险利率
- CAPM:
- 4 个月后组合的预期价值
- 指数跌幅
- 套期保值者头寸的预期总价值
Example – Hedging an Equity Portfolio
In 4 months:
- Gain from closing out the short futures position:
- Expected loss on the portfolio:
- Loss on index
- Dividend from index in 4 months
- Return on index
- Risk-free rate in 4 months
- CAPM:
- Expected value of the portfolio in 4 months
- Loss on index
- Total expected value of the hedger's position
案例分析 – 对冲股票投资组合
请注意,套期保值者头寸的 Beta 为零。
| 4 个月后的指数点位 | 5,000 | 5,200 | 5,400 | 5,600 | 5,800 | 6,000 |
|---|---|---|---|---|---|---|
| 4 个月后的指数期货价格 | 5,025 | 5,226 | 5,427 | 5,628 | 5,829 | 6,030 |
| 期货头寸的盈亏 ($) | 4,003,650 | 2,561,475 | 1,119,300 | −322,875 | −1,765,050 | −3,207,225 |
| 组合的预期收益率 (CAPM) | −6.07% | −3.16% | −0.25% | 2.65% | 5.56% | 8.47% |
| 4 个月后组合的预期价值 ($) | 46,965,000 | 48,420,000 | 49,875,000 | 51,325,000 | 52,780,000 | 54,235,000 |
| 对冲后头寸的预期价值 ($) | 50,968,650 | 50,981,475 | 50,994,300 | 51,002,125 | 51,014,950 | 51,027,775 |
图:指数对冲的绩效表现
Example – Hedging an Equity Portfolio
Note that the beta of the hedger's position is zero.
| Index level in 4 months | 5,000 | 5,200 | 5,400 | 5,600 | 5,800 | 6,000 |
|---|---|---|---|---|---|---|
| Futures price of index in 4 months | 5,025 | 5,226 | 5,427 | 5,628 | 5,829 | 6,030 |
| Gain/loss on futures position ($) | 4,003,650 | 2,561,475 | 1,119,300 | −322,875 | −1,765,050 | −3,207,225 |
| Expected return on the portfolio (CAPM) | −6.07% | −3.16% | −0.25% | 2.65% | 5.56% | 8.47% |
| Expected portfolio value in 4 months ($) | 46,965,000 | 48,420,000 | 49,875,000 | 51,325,000 | 52,780,000 | 54,235,000 |
| Expected value of hedged position ($) | 50,968,650 | 50,981,475 | 50,994,300 | 51,002,125 | 51,014,950 | 51,027,775 |
Figure: Performance of index hedge
为什么要套期保值
- 套期保值者头寸 4 个月后的收益:
- 头寸的预期价值
- 头寸的收益率
- 4 个月的无风险利率
- 头寸的预期价值
- 对冲使投资者的头寸按无风险利率增长。他/她也可以卖出股票组合,投资于无风险工具(短期国债)。那为什么还要套期保值?
- 套期保值者计划长期持有该组合,但需要短期的保护。
- 市场表现的不确定性:套期保值者只承担组合相对于市场的表现风险;套期保值消除了来自市场的风险。
- 套期保值使不利结果变得不那么不利,也使有利结果变得不那么有利。
Reasons for Hedging
- The return on the hedger's position in 4 months:
- Expected value of the hedger's position
- Return of the hedger's position
- 4-month risk-free rate
- Expected value of the hedger's position
- The hedge results in the investor's position growing at the risk-free rate. He/she could sell the portfolio and invest in risk-free instruments (T-bills). So why hedge?
- The hedger plans to hold the portfolio for a long period, but requires short-term protection.
- Uncertainty about market performance: the hedger is exposed only to the performance of the portfolio relative to the market; hedging removes the risk arising from the market.
- The hedge makes unfavourable outcomes less unfavourable and favourable outcomes less favourable.
为什么套期保值而不是直接卖出股票
- 完全对冲的股票头寸,其期望收益率等于无风险利率:
若组合相对于 CAPM 具有正的超额收益(
- 为什么不直接清仓股票、转而持有无风险短期国债?
- 保留选股的阿尔法收益:基金经理相信所选个股能跑赢基准,即使大盘整体下挫。
- 避免高额交易成本:一次性抛售 5000 万美元的组合,要承担佣金、买卖价差和市场冲击成本。
- 避免兑现资本利得税:卖出股票会立即产生纳税义务。
- 投资契约约束:养老基金和公募基金的契约通常要求保持较高的股票仓位。
Why Hedge Rather than Sell the Shares?
- The expected return on a perfectly hedged equity position is the risk-free rate:
If the portfolio earns a positive alpha relative to the CAPM (
- Why not just liquidate the stock portfolio and invest in risk-free T-bills?
- Preserve stock-selection alpha: the manager may be confident that the selected stocks will outperform their benchmarks, even during a market-wide downturn.
- Avoid large transaction costs: brokerage, bid-ask spread slippage and market impact from dumping a $50M portfolio.
- Avoid realizing capital gains tax: selling triggers immediate tax liabilities.
- Mandate and institutional constraints: pension and mutual funds often have strict mandates requiring them to remain fully invested in equities.
动态调整投资组合的 Beta 系数
- 若
- 示例:要把投资者头寸的 Beta 提高到 1.5,需要什么头寸?
- 示例:要把投资者头寸的 Beta 提高到 1.5,需要什么头寸?
- 若
- 示例:要把投资者头寸的 Beta 降低到 0.70,需要什么头寸?
- 示例:要把投资者头寸的 Beta 降低到 0.70,需要什么头寸?
Changing the Portfolio Beta
- A position in
futures contracts will change the beta of the position from
- If
- Example: what position is necessary to increase the beta of the investor's position to 1.5?
- Example: what position is necessary to increase the beta of the investor's position to 1.5?
- If
- Example: what position is necessary to reduce the beta of the investor's position to 0.70?
- Example: what position is necessary to reduce the beta of the investor's position to 0.70?
案例分析 – 调整风险敞口水平
通过建立 251 张期货合约的多头头寸,将投资者头寸的 Beta 提高到 1.5。
| 4 个月后的指数点位 | 5,000 | 5,200 | 5,400 | 5,600 | 5,800 | 6,000 |
|---|---|---|---|---|---|---|
| 4 个月后的指数期货价格 | 5,025 | 5,226 | 5,427 | 5,628 | 5,829 | 6,030 |
| 期货头寸的盈亏 ($) | −3,501,450 | −2,240,175 | −978,900 | 282,375 | 1,543,650 | 2,804,925 |
| 组合的预期收益率 (CAPM) | −6.07% | −3.16% | −0.25% | 2.65% | 5.56% | 8.47% |
| 4 个月后组合的预期价值 ($) | 46,965,000 | 48,420,000 | 49,875,000 | 51,325,000 | 52,780,000 | 54,235,000 |
| 投资者头寸的预期价值 ($) | 43,463,550 | 46,179,825 | 48,896,100 | 51,607,375 | 54,323,650 | 57,039,925 |
图:该策略的绩效表现
Example – Changing the Level of Exposure
Increase the beta of the investor's position to 1.5 by taking a long position in 251 futures contracts.
| Index level in 4 months | 5,000 | 5,200 | 5,400 | 5,600 | 5,800 | 6,000 |
|---|---|---|---|---|---|---|
| Futures price of index in 4 months | 5,025 | 5,226 | 5,427 | 5,628 | 5,829 | 6,030 |
| Gain/loss on futures position ($) | −3,501,450 | −2,240,175 | −978,900 | 282,375 | 1,543,650 | 2,804,925 |
| Expected return on the portfolio (CAPM) | −6.07% | −3.16% | −0.25% | 2.65% | 5.56% | 8.47% |
| Expected portfolio value in 4 months ($) | 46,965,000 | 48,420,000 | 49,875,000 | 51,325,000 | 52,780,000 | 54,235,000 |
| Expected value of investor's position ($) | 43,463,550 | 46,179,825 | 48,896,100 | 51,607,375 | 54,323,650 | 57,039,925 |
Figure: Performance of the Strategy
股票组合对冲与调整 Beta 系数
参数设定: 投资组合总值
当前指数 = 3,500 点 • 理论期货价格
- (a) 完全消除市场风险敞口 (
- (b) 4 个月后的大盘变动结果(指数跌至 2,800,期货价格 = 2,814.04):
净头寸受到充分保护!(期货空头收益充分弥补了股票现货端的大幅缩水)。 - (c) 将组合 Beta 降低至
Equity Portfolio Hedge & Changing Beta (ETQ 3)
Parameters: Portfolio
Current index = 3,500; theoretical futures price
- (a) Eliminate Exposure (
- (b) Outcome after 4 months (Index drops to 2,800, futures = 2,814.04):
Net position outcome is protected! (Gain on futures fully offsets equity slide). - (c) Reduce Beta to
滚动对冲策略 (逐期展期 Stack and Roll)
- 面临难题: 套期保值者面临长周期的风险敞口(例如 1 年),而市场上只有短期限的期货合约可用(例如 3 个月)。
- 应对策略:
- 在近期活跃合约上建立初始对冲头寸。
- 在临近合约到期日之前,对冲平仓原有合约,并在下一期活跃合约上建立新的对冲头寸(向前展期滚动)。
- 展期基差风险 (Roll-over Basis Risk):
- 保值者在每次合约展期平仓和新开仓时,都会承担新的基差波动风险。
- 最著名的历史案例为 Metallgesellschaft (MG,1993年):该公司在原油市场处于长期升水 (Contango) 结构下,对巨额长达10年的能源供货合同实施短期期货滚动对冲,展期损失导致数十亿美元灾难性亏损。
Rolling the Hedge Forward (Stack and Roll)
- The Problem: Suppose one has a long-dated exposure (e.g., 1 year) and only short-dated futures contracts are available (e.g., 3 months).
- The Strategy:
- Take a hedge position in short-dated contracts.
- Just before maturity, close out existing contracts and open a new position in the next contract (rolling forward).
- Roll-over Basis Risk:
- Each time a contract is rolled over, the hedger incurs basis risk at that rollover point.
- Made famous by Metallgesellschaft (1993), which suffered massive losses on rolling forward short oil hedges during market contango.