Delta (
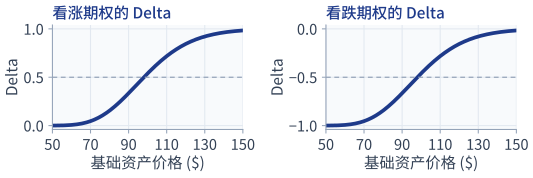
- 定义: Delta 是期权价格
- 无红利资产的欧式看涨与看跌期权:
- Delta 取值范围:
- 看涨期权 Delta 介于
- 看跌期权 Delta 介于
- 看涨期权 Delta 介于
Delta (
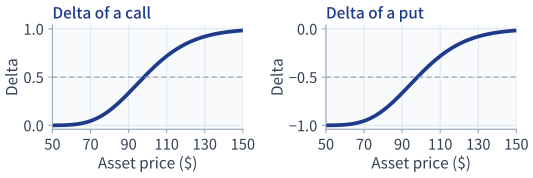
- Definition: Delta is the rate of change of the option price
- European Calls and Puts on Non-Dividend Paying Assets:
- Delta Ranges:
- Call Delta lies between
- Put Delta lies between
- Call Delta lies between
Delta 的核心性质
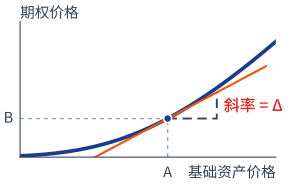
- 斜率的几何含义: Delta 是期权价格关于基础资产价格
- 请与上一页的 Delta 曲线对照理解。
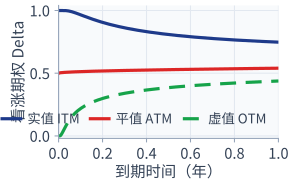
- Delta 与到期时间的关系:
- 当到期时间
- 对于实值看涨期权(
- 对于虚值看涨期权(
- 对于平值看涨期权(
- 对于实值看涨期权(
- 当到期时间
Properties of Delta
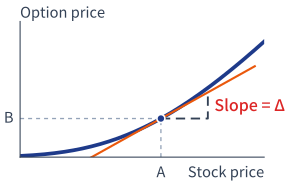
- Slope Interpretation: Delta is the slope of the curve plotting option price against the underlying asset price
- Relate this to the previous graphs.
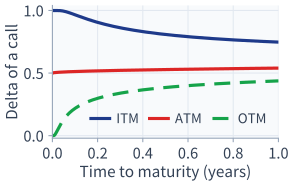
- Relation between Delta and Time to Maturity:
- As time to maturity
- For an ITM call (
- For an OTM call (
- For an ATM call (
- For an ITM call (
- As time to maturity
Theta 的性质与特征
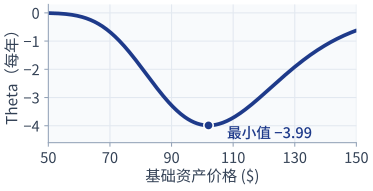
- Theta 与基础资产价格的关系:
- 参数设定:
- 当期权处于平值状态(
- 对于深度实值或深度虚值期权,Theta 趋近于 0(因为期权价格被内在价值主导,或者外在时间价值本身极小)。
- 参数设定:
- Theta 与到期时间的关系:
- 对于平值期权,随着到期日临近(
- 交易员持有临近到期的平值多头期权时,必须警惕严峻的日度时间价值侵蚀。
- 对于平值期权,随着到期日临近(
Properties of Theta
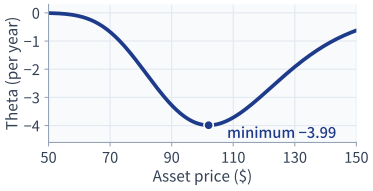
- Relation between Theta and the underlying asset price:
- Parameters:
- Theta is most negative (time value decays fastest) when the option is at-the-money (
- For deep ITM or deep OTM options, Theta approaches 0 (because the option price is dominated by intrinsic value, or the time value itself is tiny).
- Parameters:
- Relation between Theta and time to maturity:
- For ATM options, time decay accelerates sharply as expiration approaches (
- Traders holding near-expiry ATM long options must watch out for severe daily time-value erosion.
- For ATM options, time decay accelerates sharply as expiration approaches (
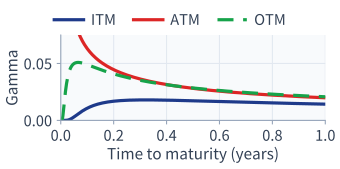
Gamma 的性质
- 虚实值程度对 Gamma 的影响:
- 深度虚值(Deep OTM): Delta
- 平值状态(ATM): Delta
- 深度实值(Deep ITM): Delta
- 深度虚值(Deep OTM): Delta
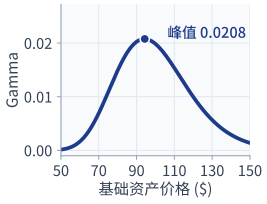
- Gamma 与基础资产价格的关系:
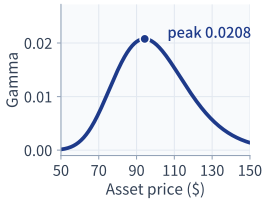
Gamma 随基础资产价格呈现尖锐的钟形曲线,在执行价格附近(略低于
- 对冲者必须高度关注持有平值期权的组合,其 Gamma 风险极为集中。
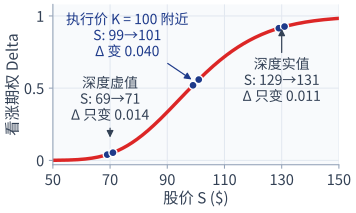
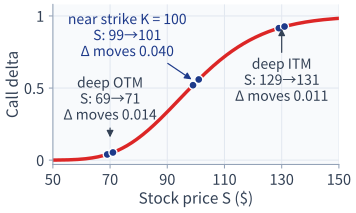
- 左图:股价同样变动 $2,看涨期权的 Delta 只在执行价
Properties of Gamma
- Moneyness Effect on Gamma:
- Deep OTM: Delta
- At-the-Money (ATM): Delta
- Deep ITM: Delta
- Deep OTM: Delta
- Relation between Gamma and Asset Price:
The curve of Gamma against asset price forms a sharp bell-shaped peak close to the strike price (slightly below
- Hedgers must be especially attentive to portfolios with ATM options where Gamma risk is concentrated.
- Left chart: the same $2 move in the stock price changes the call's delta a lot only near the strike
Gamma 的性质与曲率修正
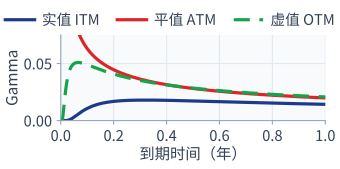
- Gamma 与到期时间的关系:
- 当
- 当
- Gamma 刻画了 Delta 对冲中的二阶曲率效应:
- 若
- 若
- 若
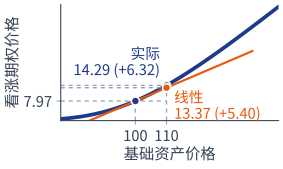
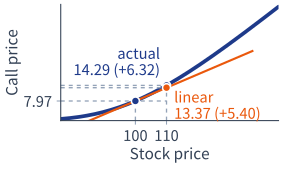
- 曲率增益直观示例:
在
一阶线性 Delta 预测值:
加入 Gamma 修正:
考虑非线性曲率后的实际看涨期权价格(BSM):
约 +$1 的修正项(
Properties of Gamma & Curvature
- Relation between Gamma and time to maturity:
- As
- As
- Gamma accounts for curvature in delta hedging:
- If
- If
- If
- Curvature Gain Illustration:
At
Linear Delta prediction:
With Gamma correction:
Actual call price with curvature (BSM):
The ~+$1 correction (
Delta、Theta 与 Gamma 之间的内在关系
一句话:Delta 对冲只消除股价小幅变动的风险;剩下的是押注股价“大动”还是“不动”。
| 头寸方向 | Delta | ||
|---|---|---|---|
| 多头看涨 | + | + | − |
| 多头看跌 | − | + | − |
| 空头看涨 | − | − | + |
| 空头看跌 | + | − | + |
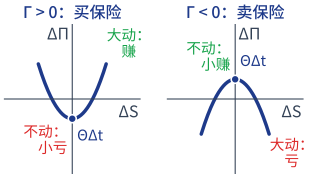
对 Delta 中性组合(组合 Delta
- 买入期权并对冲(
- 卖出期权并对冲(
Relationship between Delta, Theta and Gamma
In one line: delta hedging removes only the risk of small moves; what is left is a bet on big moves versus no moves.
| Position | Delta | ||
|---|---|---|---|
| Long Call | + | + | − |
| Long Put | − | + | − |
| Short Call | − | − | + |
| Short Put | + | − | + |
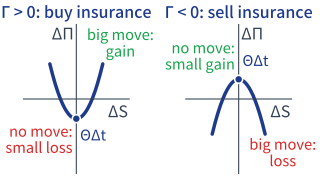
Taylor expansion for a delta-neutral portfolio (portfolio Delta
- Buy options and hedge (
- Sell options and hedge (
Vega (
- 定义: Vega 是期权价格
- 欧式看涨与看跌期权公式(两者完全相同):
其中
- 无论看涨期权多头还是看跌期权多头,Vega 恒为正值。
- 经济含义: 若波动率
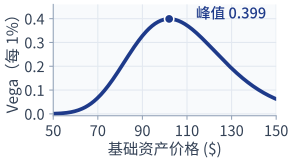
- Vega 与基础资产价格的关系(见下图):平值期权(ATM)的 Vega 达到最高,随着深入实值或虚值逐渐下降。
Vega (
- Definition: Vega is the rate of change of option price
- Formula for European Call and Put (identical for both):
where
- Vega is strictly positive for both long calls and long puts.
- Interpretation: If volatility
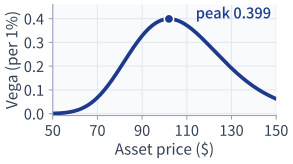
- Relation between Vega and asset price (chart below): Vega is highest for at-the-money options and drops off for deep ITM/OTM options.
裸空头头寸 (Naked Position)
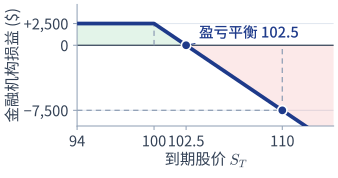
- 采取裸空头看涨期权时,金融机构不采取任何对冲措施,直接留存初始收取的 $2,500 权利金。
- 到期损益特征:
- 若
- 若
- 若
- 数值示例: 假设
- 结论: 裸卖空看涨期权使机构暴露于不可控的巨额上行市场风险之中。
Naked Position
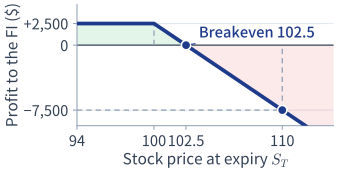
- With a naked short call, the institution takes no hedging action and simply keeps the initial premium of $2,500.
- P&L Profile at Expiration:
- If
- If
- If
- Numerical Example: Suppose
- Conclusion: Writing naked calls exposes the institution to uncontrollable, large upside market risk.
备兑头寸 (Covered Position)
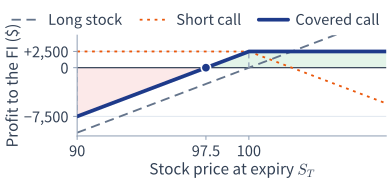
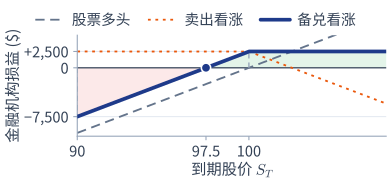
- 备兑看涨期权策略(Covered Call,见第 7 讲): 卖出 1,000 份看涨期权 + 以
- 损益特征:
- 若
- 若
- 若
- 数值示例: 假设
- 结论: 卖出备兑看涨期权仅仅是将上行风险转换成了严重的下行风险 – 根据买卖权平价定理,这在本质上等价于卖出裸看跌期权!
Covered Position
- Covered Call Strategy (see Lecture 7): Sell 1,000 call options + buy 1,000 shares at
- P&L Profile:
- If
- If
- If
- Numerical Example: Suppose
- Conclusion: Writing a covered call merely converts upside risk into severe downside risk – by put-call parity, this is essentially equivalent to writing a naked put!