← 目录Index 第 1 讲:金融衍生品市场导论Lecture 1 · Introduction to Derivatives Markets 幻灯片Slides
本讲目录Contents
  1. 学习目标Learning Objectives
  2. 衍生品本质Nature of Derivatives
  3. 衍生品市场Derivatives Markets
  4. 远期合约Forward Contracts
  5. 期货合约Futures Contracts
  6. 期权导论Options
  7. 衍生品用途Derivatives Uses
  8. 套期保值Hedging
  9. 投机策略Speculation
  10. 套利机制Arbitrage
第 1 页幻灯片 ↗
第 1 讲
金融衍生品市场导论
Hull 著,第 1 & 2 章
本周核心要点
  • 远期合约属于场外交易 (OTC) 合约
  • 期货合约每日进行结算 – 逐日盯市 (Mark to Market)
  • 期权买方需要支付期权费 / 权利金 (Premium)
UTS
Page 1Slide ↗
Lecture 1
Introduction to Derivatives Markets
Hull, Chapters 1 & 2
Tip of the week
  • Forwards are OTC contracts
  • Futures are settled daily – mark to market
  • Options require premium
UTS
第 2 页 · 学习目标幻灯片 ↗

学习目标

  • 阐述远期合约、期货合约以及期权合约的基本特征
  • 概述场内交易所市场与场外交易 (OTC) 市场
  • 探讨期货市场机制
    • 解释每日逐日盯市 (Marking-to-Market) 结算流程
    • 结合保证金账户交易细则讨论保证金运作机制
    • 定义并对比正常市场与反向市场 – 升水 (Contango) 与贴水 (Backwardation)
  • 解释衍生品市场参与者的经济活动:
    • 套期保值者 (Hedgers) • 投机者 (Speculators) • 套利者 (Arbitrageurs)
  • 分析基础套利机会与定价边界
Page 2 · Learning ObjectivesSlide ↗

Learning Objectives

  • Describe the basic characteristics of forward, futures and option contracts
  • Overview exchange markets and over-the-counter markets
  • Discuss futures markets
    • Explain the daily marking-to-market process
    • Discuss the margin process with reference to margin account transactions
    • Define and contrast normal markets and inverted markets – backwardation and contango
  • Explain the activities of the derivatives users:
    • Hedgers • Speculators • Arbitrageurs
  • Analyze basic arbitrage opportunities
第 3 页 · 学习目标幻灯片 ↗

前置基础知识

25556 金融证券 (FS) – 第 10 讲:金融期货
  • 阐述期货的本质及其与远期合约的关系
  • 理解套期保值者和投机者如何利用期货市场
  • 阐述悉尼期货交易所 (SFE) 采用的交易与结算安排
  • 理解以下期货合约,并说明如何用它们进行套期保值
    • BAB 期货(银行承兑汇票期货)
    • SPI 期货(股价指数期货)
课程衔接:在本课程中,我们将在该基础之上严格展开深入分析,推导严密的持有成本方程 (Cost of Carry)、便利收益率 (Convenience Yield)、看涨-看跌期权平价套利边界以及实证最优对冲比率。
Page 3 · Learning ObjectivesSlide ↗

Assumed Knowledge

25556 FS – Lecture 10: Financial Futures
  • Explain the nature of futures and their relationship to forwards
  • Understand how the futures market can be used by hedgers and speculators
  • Explain the trading and settlement arrangements used by the SFE (Sydney Futures Exchange)
  • Understand the following futures contracts and explain how they can be used for hedging
    • BAB futures (bank accepted bills)
    • SPI futures (Share Price Index)
Foundation Link: In 20762, we build rigorously on this foundation by developing exact cost of carry equations, convenience yields, put-call parity arbitrage bounds, and empirical hedge ratios.
第 4 页 · 衍生品本质幻灯片 ↗

衍生品的本质

  • 衍生品 (Derivative) 是一种金融工具,其价值取决于(或衍生自)另一种更基础的资产的价值。这种资产叫基础资产 (Underlying Asset),教材里也常叫“标的资产”。
  • 四大基础衍生工具模块:
    • 期货合约 (Futures Contracts): 在交易所集中交易的标准化协议,约定在未来特定日期以特定价格买入或卖出基础资产。
    • 远期合约 (Forward Contracts): 在场外市场 (OTC) 私下达成的双边定制协议,约定在未来买入或卖出基础资产。
    • 互换合约 (Swaps): 双方私下达成的协议,约定在未来多个日期之间周期性互换现金流。
    • 期权合约 (Options): 赋予买方在未来特定日期或之前以约定价格买入(看涨期权)或卖出(看跌期权)基础资产的权利(而非义务)的合约。
Page 4 · Nature of DerivativesSlide ↗

The Nature of Derivatives

  • A derivative is a financial instrument whose value depends on (or derives from) the values of other, more basic underlying assets.
  • Four fundamental derivative building blocks:
    • Futures contracts: Standardised exchange-traded agreements to buy/sell at a specified future date and price.
    • Forward contracts: Customised bilateral over-the-counter (OTC) agreements to buy/sell in the future.
    • Swaps: Private agreements between two parties to exchange periodic cash flows over multiple dates.
    • Options: Contracts conferring the right (without obligation) to buy (call) or sell (put) an asset.
第 5 页 · 衍生品本质幻灯片 ↗

基础资产

  • 金融证券
    • 股票、债券、货币、股票指数
  • 大宗商品
    • 金属(铜、黄金、白银)
    • 农产品(玉米、棉花、橙汁、咖啡、活牛)
    • 木材
  • 能源
    • 石油产品、天然气、电力
  • 其他 – 保险、天气、信用

投资性资产,还是消费性资产?

  • 投资性资产 (Investment Asset):许多投资者纯粹出于投资目的而持有(如黄金、白银)。
  • 消费性资产 (Consumption Asset):主要为消费而持有(如石油、铜)。
Page 5 · Nature of DerivativesSlide ↗

Underlying Asset

  • Financial Securities
    • Stocks, bonds, currencies, stock indices
  • Commodities
    • Metals (copper, gold, silver)
    • Agricultural (corn, cotton, orange juice, coffee, cattle)
    • Wood
  • Energy
    • Oil products, natural gas, electricity
  • Other – Insurance, weather, credit

Investment Asset OR Consumption Asset ?

  • Investment assets are held by many investors purely for investment (e.g. gold, silver).
  • Consumption assets are held primarily for consumption (e.g. oil, copper).
第 6 页 · 衍生品市场幻灯片 ↗

衍生品交易所

交易期货的交易所交易期权的交易所
芝加哥期货交易所 (CBOT,1865 年)芝加哥期权交易所 (CBOE)
芝加哥商业交易所 (CME)费城证券交易所
LIFFE(伦敦国际金融期货交易所,伦敦)LIFFE(伦敦)
Eurex(欧洲期货交易所,欧洲)Eurex(欧洲)
SFE(悉尼期货交易所)
1960 年首笔交易(羊毛期货)
2002 年在 ASX 上市
ASX(澳大利亚证券交易所)
1976 年首笔期权交易(BHP 看涨期权)
1982 年首批看跌期权
  • 优点:提供交割日期多样的标准化合约;没有信用风险
  • 缺点:需要缴纳保证金;无法按需定制合约
Page 6 · Derivatives MarketsSlide ↗

Derivatives Exchanges

Exchanges Trading FuturesExchanges Trading Options
Chicago Board of Trade (1865)Chicago Board Options Exchange
Chicago Mercantile ExchangePhiladelphia Stock Exchange
LIFFE (London)LIFFE (London)
Eurex (Europe)Eurex (Europe)
SFE (Sydney)
1st trade in 1960 (Wool futures)
Listed on ASX: 2002
ASX
1st options trade in 1976 (BHP calls)
1st put options in 1982
  • Advantages: provide standardized contracts on a range of delivery dates; no credit risk
  • Disadvantages: attract margin requirements; no freedom to tailor contracts
第 7 页 · 衍生品市场幻灯片 ↗

场外交易 (OTC) 市场

  • 交易所之外的重要替代渠道
  • 由交易商组成、通过电话和计算机联网的交易网络,交易商无需实际碰面
  • 交易通常发生在金融机构、企业财务主管和基金经理之间
  • 优点
    • 更大的自由度 – 合约条款可根据客户需求量身定制(不受交易所规格限制)
    • 无需缴纳保证金
  • 缺点
    • 信用风险(一方不履约的风险;通常适用 ISDA 主协议);可通过抵押品(担保)降低
  • 2008 年以来 …
    • 场外市场已纳入监管
    • 标准化的场外产品在互换执行设施 (SEF) 上交易
    • 所有交易必须向中央数据库报告
Page 7 · Derivatives MarketsSlide ↗

Over-the-Counter (OTC) Markets

  • Important alternative to exchanges
  • Telephone and computer-linked network of dealers who do not meet physically
  • Trades are usually between financial institutions, corporate treasurers, and fund managers
  • Advantages
    • More freedom – contract terms are tailored to the needs of the client (not exchange specific)
    • No need for margin payments
  • Disadvantages
    • Credit risk (the risk that one of the parties will not honor the contract; documented under ISDA Master Agreements); this can be reduced by collateralization
  • Since 2008 …
    • OTC markets have become regulated
    • Standardized OTC products trade on swap execution facilities (SEFs)
    • All trades must be reported to a central registry
第 8 页 · 衍生品市场幻灯片 ↗

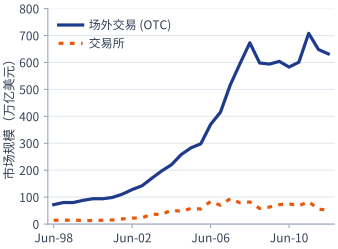
场外衍生品与场内衍生品市场规模

场外与场内衍生品市场规模(万亿美元),1998 年 6 月至 2012 年 6 月

资料来源:国际清算银行 (BIS)。图中场外市场为名义本金总额,交易所市场为基础资产价值。
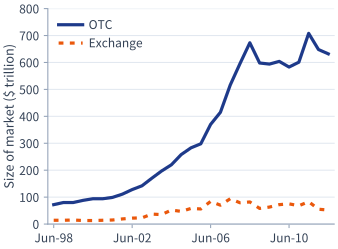
  • 名义本金 (Notional Principal):用于计算衍生品现金流的参考金额。
Page 8 · Derivatives MarketsSlide ↗

Size of OTC and Exchange Traded Derivatives Markets

Size of the OTC and exchange-traded derivatives markets in $ trillion, June 1998 to June 2012

Source: Bank for International Settlements. Chart shows total principal amounts for OTC markets and value of underlying assets for exchange markets.

  • Notional principal: the reference dollar amount on which derivative cash flows are calculated.
第 9 页 · 远期合约幻灯片 ↗

远期合约

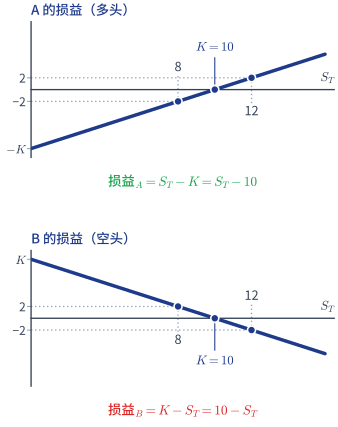
远期合约是一种场外 (OTC) 协议,约定在未来某一时间 T 按某一价格 K(远期价格)买入或卖出某种资产。

  • 同意买入的一方 A 持有多头头寸 (Long Position)。
  • 同意卖出的一方 B 持有空头头寸 (Short Position)。
  • 订立远期合约在初始时刻不需要任何前期现金流支出(初始时刻合约价值 f0=0)。图中 ST 为到期日 T 的现货价格。
远期合约多头 A 与空头 B 的损益(K = 10)
Page 9 · Forward ContractsSlide ↗

Forward Contracts

A forward contract is an OTC agreement to buy or sell an asset at a certain time T in the future for a certain price K – the forward price.
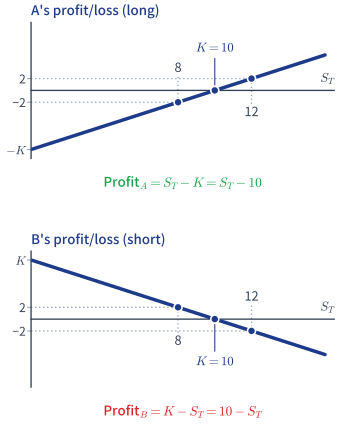
  • The party A that has agreed to buy has a long position.
  • The party B that has agreed to sell has a short position.
  • Entering a forward contract requires zero upfront cash flow (the contract value at initiation f0=0). In the chart, ST is the spot price at maturity T.
Profit or loss of the long party A and the short party B of a forward contract with K = 10
第 10 页 · 期货合约幻灯片 ↗

期货合约

期货合约是一种协议,约定在未来某一时间 T 按某一价格(期货价格 Ft,t 为某一时点,t=0 为今天)买入或卖出某种资产。

  • 期货价格在今天观察到,但对应的是将在未来进行的交易
    • 期货价格由供求关系决定,与现货价格的决定方式相同
  • 期货合约在交易所交易
    • 交易所规定交割日 T,并规定以交割基础资产(商品期货)或现金结算(金融期货)的方式了结
    • 每日结算:逐日盯市 (Marking-to-Market)
    • 结算所通过合约更替 (Novation) 保证双方履约(成为每一位买方的卖方,以及每一位卖方的买方)
  • 绝大多数期货合约在到期前被平仓,而不是实物交割。平仓是指进行一笔对冲(反向)交易
    • 并由此产生现金盈亏
Page 10 · Futures ContractsSlide ↗

Futures Contracts

A futures contract is an agreement to buy or sell an asset at a certain time T in the future for a certain price – the futures price Ft (t is a point in time; t=0 is today).

  • Futures prices are observed today but refer to transactions to be carried out in the future
    • Futures price is determined by supply and demand, in the same way as the spot price
  • Futures contracts are traded on exchanges
    • The exchange specifies delivery date T and settlement by delivery of the underlying (commodity futures) or by cash settlement (financial futures)
    • Are settled daily: marking-to-market
    • The clearinghouse guarantees both sides by novation (buyer to every seller, seller to every buyer)
  • Most futures contracts are closed out before maturity, rather than settled by physical delivery. Closing out a futures position involves entering into an offsetting trade
    • resulting in a cash profit or loss
第 11 页 · 期货合约幻灯片 ↗

核心机制差异:远期合约 vs 期货合约

比较维度 远期合约 (Forward Contract) 期货合约 (Futures Contract)
交易场所 场外交易市场 OTC (私下双边协商) 规范化交易所 (如 CME、ASX、ICE)
合约条款 根据用户个性化需求量身定制 高度标准化 (规模、交割品、日期)
结算方式 到期日 T 一次性结算 每日结算 (逐日盯市 Mark to Market)
信用风险 存在显著的交易对手违约风险 由结算所清算担保,基本被消除
提前平仓 较为困难;需征得原对手方同意 在流动性充裕的市场上随时对冲平仓

核心机制总结: 期货利用结算所保证金制度替代了个体交易对手信用风险。由于每日损益都在当日现金结算结清,违约敞口无法像双边远期协议那样跨越数月累积扩大。

Page 11 · Futures ContractsSlide ↗

Core Structural Differences: Forwards vs Futures

Dimension Forward Contract Futures Contract
Trading Arena Over-The-Counter (private bilateral) Organised Exchange (CME, ASX, ICE)
Contract Terms Customised to user needs Standardised (size, delivery, date)
Settlement Single settlement at maturity T Marked to market daily
Credit Risk Significant counterparty risk Virtually eliminated by Clearinghouse
Closing Out Difficult; requires counterparty consent Immediate offset in liquid market

Futures replace individual counterparty risk with clearinghouse margin capital. Because gains and losses are realized daily, default exposure cannot accumulate across months as it does in bilateral forward agreements.

第 12 页 · 期货合约幻灯片 ↗

期货价格的演变

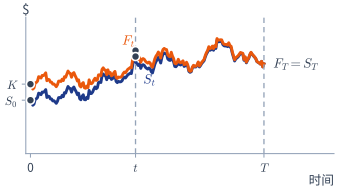
随着时间推移,市场参与者持续交易在 T 时刻买入/卖出资产的期货合约。

  • 现货价格 St 是资产在 t 时刻立即交割的价格(S0 为今天的现货价格)
  • 期货价格 Ft 是在 t 时刻订立、于 T 时刻交割资产的期货合约所约定的交割价格
从时刻 0 到 T 的现货与期货价格路径:t 时刻的 F_t 与 S_t,交割时 F_T = S_T

注意 F0=K

  • 由于期货合约的卖方可以在到期时交割实物资产,期货价格与现货价格在到期时必须相等(FT=ST)。否则,套利者可以获得无风险利润:
    • FT>ST:买入现货、做空期货并交割,利润为 FT−ST
    • FT<ST:卖空资产、买入期货并接受交割,利润为 ST−FT
Page 12 · Futures ContractsSlide ↗

Evolution of Futures Price

As time goes by, market participants continue trading futures contracts to buy/sell the asset at T.
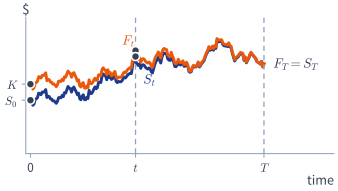
  • The spot price St is the asset price at time t for immediate delivery (S0 is today's spot price)
  • The futures price Ft is the agreed delivery price for a futures contract initiated at t, for asset delivery at T
Spot and futures price paths from time 0 to T: F_t and S_t at time t, F_T = S_T at delivery

Note that F0=K

  • Since the seller of the futures contract can deliver the physical asset at maturity, the futures price and the spot price must be the same at that time (FT=ST). If not, arbitrageurs could make risk-free profits:
    • FT>ST: buy the asset spot, short futures, deliver; profit FT−ST
    • FT<ST: short sell the asset, buy futures, take delivery; profit ST−FT
第 13 页 · 期货合约幻灯片 ↗

保证金制度与要求

  • 保证金是投资者存入其经纪人账户的现金或可流通证券;它是履约担保 (Performance Bond),而非贷款或购货首付款
    • 初始保证金 (Initial Margin):开仓时存入
    • 维持保证金 (Maintenance Margin):触发追加保证金通知前账户的最低余额(通常约为初始保证金的 75%–80%)
    • 追加保证金通知(变动保证金,Margin Call):余额跌破维持保证金时,投资者必须存入资金,将余额恢复至初始保证金水平
  • 保证金账户余额随每日结算(逐日盯市)而调整
  • 保证金账户可以获得利息
  • 保证金通过减少违约时的损失来控制信用风险
  • 结算所(SFE 结算公司,Clearinghouse)
    • 经纪商在结算所持有结算保证金账户
    • 对所有会员的头寸进行净额结算,并记录当天的全部交易
Page 13 · Futures ContractsSlide ↗

Margin Requirements

  • A margin is cash or marketable securities deposited by an investor with his/her broker; it is a performance bond, not a loan or down payment
    • Initial margin: deposited when the position is opened
    • Maintenance margin: the minimum balance before a margin call (typically about 75–80% of initial margin)
    • Margin call (variation margin): if the balance falls below maintenance margin, the investor must deposit funds to restore it to the initial margin
  • The balance in the margin account is adjusted to reflect daily settlement (marking-to-market)
  • Interest is earned on margin accounts
  • Margins control credit risk, by reducing the loss in the event of default
  • Clearinghouse (SFE Clearing Corporation)
    • Broker holds a clearing margin account with the Clearinghouse
    • Netting positions of all members and keep track of all transactions in one day
第 14 页 · 期货合约幻灯片 ↗

案例分析 – 保证金账户运作

  • 6 月 5 日:投资者买入 2 张 12 月到期黄金期货合约(多头)
    • 合约规模 = 100 盎司
    • 期货价格 = 400 美元
    • 初始保证金 = 每张合约 2,000 美元,合计 4,000 美元
    • 维持保证金 = 每张合约 1,500 美元,合计 3,000 美元
  • 6 月 26 日:投资者通过卖出 2 张 12 月到期黄金期货合约(空头)平仓
    • 期货价格 = 392.30 美元
  • 投资者亏损 = (392.30 − 400) × 200 = 1,540 美元
Page 14 · Futures ContractsSlide ↗

Example – Margin Accounts

  • On June 5: investor enters a long position in two December gold futures contracts
    • Contract size = 100 oz
    • Futures price = USD 400
    • Initial margin = USD 2,000 per contract or USD 4,000 in total
    • Maintenance margin = USD 1,500 per contract or USD 3,000 in total
  • On June 26: investor closes out the position by entering a short position in two December gold futures contracts
    • Futures price = USD 392.30
  • Investor loss = USD (392.30 − 400) × 200 = USD 1,540
第 15 页 · 期货合约幻灯片 ↗

案例分析 – 保证金账户运作

日期期货价格 ($)当日盈亏 ($)累计盈亏 ($)保证金账户余额 ($)追加保证金 ($)
400.004,000
6月5日397.00(600) = 2 × $3 × 100 盎司(600)3,400
6月6日396.10(180)(780)3,220
6月9日398.20420(360)3,640
6月10日397.10(220)(580)3,420
6月11日396.70(80)(660)3,340
6月12日395.40(260)(920)3,080
6月13日393.30(420)(1,340)2,6601,340
6月16日393.6060(1,280)4,060
6月17日391.80(360)(1,640)3,700
6月18日392.70180(1,460)3,880
6月19日387.00(1,140)(2,600)2,7401,260
6月20日387.000(2,600)4,000
6月23日388.10220(2,380)4,220
6月24日388.70120(2,260)4,340
6月25日391.00460(1,800)4,800
6月26日392.30260(1,540)5,060
6 月 13 日账户余额 (2,660) 跌破 3,000 的维持保证金,因此追加保证金 1,340,使余额恢复到 4,000 的初始保证金;6 月 19 日同理追加 1,260。
Page 15 · Futures ContractsSlide ↗

Example – Margin Accounts

DayFutures Price ($)Daily Gain (Loss) ($)Cumulative Gain (Loss) ($)Margin Account Balance ($)Margin Call ($)
400.004,000
June 5397.00(600) = 2 × $3 × 100 oz(600)3,400
June 6396.10(180)(780)3,220
June 9398.20420(360)3,640
June 10397.10(220)(580)3,420
June 11396.70(80)(660)3,340
June 12395.40(260)(920)3,080
June 13393.30(420)(1,340)2,6601,340
June 16393.6060(1,280)4,060
June 17391.80(360)(1,640)3,700
June 18392.70180(1,460)3,880
June 19387.00(1,140)(2,600)2,7401,260
June 20387.000(2,600)4,000
June 23388.10220(2,380)4,220
June 24388.70120(2,260)4,340
June 25391.00460(1,800)4,800
June 26392.30260(1,540)5,060
On June 13 the balance (2,660) falls below the 3,000 maintenance margin, so the margin call of 1,340 restores it to the 4,000 initial margin; likewise 1,260 on June 19.
第 16 页 · 期货合约幻灯片 ↗

E-Mini 标普500 追加保证金逐步计算案例

参数设定: 交易者 A 以 2,800 点买入多头 1 张 E-Mini S&P 500 期货合约。合约乘数 = $50/指数点。名义价值 = 2,800×$50=$140,000。
初始保证金 = $5,500 • 维持保证金 = $5,000 • 账户初始资金 = $5,500。

  • 第 1 天: 指数下跌 5 点。当日损失 = 5×$50=$250。账户余额降至 $5,500−$250=$5,250(高于 $5,000 维持线 → 无需追加保证金)。
  • 第 2 天: 指数继续下跌 10 点。新增损失 = 10×$50=$500。账户余额降至:
    账户余额=$5,250−$500=$4,750<$5,000 ⟹触发追加保证金通知 (Margin Call)!
  • 应追加变动保证金额度:
    追加保证金=$5,500−$4,750=$750

重要区分: 投资者必须注入 $750 将账户余额恢复至 初始保证金 $5,500,而绝不能只追加 $250 恢复到维持保证金!

Page 16 · Futures ContractsSlide ↗

Step-by-Step E-Mini S&P 500 Margin Call Calculation

Contract Parameters (from video): Trader A goes LONG 1 E-Mini S&P 500 contract at 2,800. Multiplier = $50/point. Notional value = 2,800×$50=$140,000.
Initial Margin = $5,500 • Maintenance Margin = $5,000 • Starting balance = $5,500.

  • Day 1: Index falls 5 points. Loss = 5×$50=$250. Balance drops to $5,500−$250=$5,250 (above $5,000 maintenance → No call).
  • Day 2: Index falls another 10 points. Additional loss = 10×$50=$500. Balance drops to:
    Balance=$5,250−$500=$4,750<$5,000 ⟹Margin Call Triggered!
  • Required Margin Deposit:
    Variation Margin=$5,500−$4,750=$750

Critical Distinction: The investor must deposit $750 to bring the balance back to the initial margin of $5,500, NOT merely $250 to reach maintenance margin!

第 17 页 · 期货合约幻灯片 ↗

交互实验:保证金账户逐日结算

黄金和 E-Mini 两个例子的价格都已填好。点“重置”后逐日点“下一天”,看余额怎么变;把某一天的价格改低,让余额跌破维持保证金,注意追加的钱补回的是初始保证金。 新窗口全屏打开 ↗

Page 17 · Futures ContractsSlide ↗

Interactive Margin Account

Click “Reset”, then “Next day” to step through the gold and E-Mini examples. Lower a price until the balance triggers a margin call: the deposit restores the initial margin. Open in New Window ↗

第 18 页 · 期货合约幻灯片 ↗

期货价格的形态

远期曲线给出某一天不同到期期限的期货价格。

黄金 (GOLD)
合约月份最新价涨跌开盘最高最低成交量持仓量交易所
黄金2011年7月1612.0y6740COMX
黄金2011年8月1614.92.71614.81615.51611.112261193611COMX
黄金2011年9月1615.62.71614.31616.11612.9629255COMX
黄金2011年10月1615.82.51616.11616.41612.816617547COMX
黄金2011年12月1617.32.91616.11617.71613.44876216137COMX
黄金2012年2月1617.51.71618.01618.01617.51911520COMX
黄金2012年4月1619.42.11616.71619.41616.746165COMX

图:2011 年 7 月 25 日 COMEX 黄金期货合约行情(来源:ifs.marketcenter.com)

  • 正常市场 (Normal Market)
    • 远期曲线向上倾斜
    • 近月期货价格低于远月期货价格
    • 市场处于期货升水 (Contango):期货价格高于现货价格
Page 18 · Futures ContractsSlide ↗

Patterns of Futures Prices

The forward curve gives the futures prices on a given day, for a range of different maturities.

GOLD
ContractMonthLastChgOpenHighLowVolumeOpenIntExchange
GOLDJul '111612.0y6740COMX
GOLDAug '111614.92.71614.81615.51611.112261193611COMX
GOLDSep '111615.62.71614.31616.11612.9629255COMX
GOLDOct '111615.82.51616.11616.41612.816617547COMX
GOLDDec '111617.32.91616.11617.71613.44876216137COMX
GOLDFeb '121617.51.71618.01618.01617.51911520COMX
GOLDApr '121619.42.11616.71619.41616.746165COMX

Figure: Listing for COMX gold futures contracts on 25 July 2011 (Source: ifs.marketcenter.com)

  • Normal market
    • Forward curve is upward sloping
    • Futures prices for near months are lower than for later months
    • The market is in contango: futures prices trade higher than spot prices
第 19 页 · 期货合约幻灯片 ↗

期货价格的形态

轻质原油 (LIGHT CRUDE OIL)
合约月份最新价涨跌开盘最高最低成交量持仓量交易所日期时间
轻质原油2013年8月101.09-0.15101.09101.49100.7119380258114NYME07/04/1313:38:49
轻质原油2013年9月100.93-0.18100.95101.31100.544865230505NYME07/04/1313:38:49
轻质原油2013年10月99.80-0.2699.88100.1899.44206896887NYME07/04/1313:24:06
轻质原油2013年11月98.61-0.3698.7899.0598.36115872866NYME07/04/1313:05:42
轻质原油2013年12月97.51-0.3997.9097.9397.172294217091NYME07/04/1313:22:19
轻质原油2014年1月96.36-0.4996.6296.6896.2937655486NYME07/04/1313:38:14
轻质原油2014年2月95.60-0.2995.6095.6095.6016231218NYME07/04/1303:19:02
轻质原油2014年3月94.29-0.7694.7194.7194.2923749487NYME07/04/1311:53:59

图:2013 年 7 月 4 日 NYMEX 原油期货合约行情(来源:ifs.marketcenter.com)

  • 反向市场 (Inverted Market)
    • 远期曲线向下倾斜
    • 远月期货价格低于近月期货价格
    • 市场处于期货贴水 (Backwardation):期货价格低于现货价格
Page 19 · Futures ContractsSlide ↗

Patterns of Futures Prices

LIGHT CRUDE OIL
ContractMonthLastChgOpenHighLowVolumeOpenIntExchangeDateTime
LIGHT CRUDE OILAug '13101.09-0.15101.09101.49100.7119380258114NYME07/04/1313:38:49
LIGHT CRUDE OILSep '13100.93-0.18100.95101.31100.544865230505NYME07/04/1313:38:49
LIGHT CRUDE OILOct '1399.80-0.2699.88100.1899.44206896887NYME07/04/1313:24:06
LIGHT CRUDE OILNov '1398.61-0.3698.7899.0598.36115872866NYME07/04/1313:05:42
LIGHT CRUDE OILDec '1397.51-0.3997.9097.9397.172294217091NYME07/04/1313:22:19
LIGHT CRUDE OILJan '1496.36-0.4996.6296.6896.2937655486NYME07/04/1313:38:14
LIGHT CRUDE OILFeb '1495.60-0.2995.6095.6095.6016231218NYME07/04/1303:19:02
LIGHT CRUDE OILMar '1494.29-0.7694.7194.7194.2923749487NYME07/04/1311:53:59

Figure: Listing for NYMEX crude oil futures contracts on 4 July 2013 (Source: ifs.marketcenter.com)

  • Inverted market
    • Forward curve is downward-sloping
    • Futures prices for distant months are lower than for near months
    • The market is in backwardation: futures prices trade lower than spot prices
第 20 页 · 期货合约幻灯片 ↗

黄金远期曲线解读与市场预期

案例设定: COMEX 黄金期货行情(2009年2月2日):2月 $907.00,4月 $909.50,6月 $912.40,8月 $915.20,10月 $918.00,12月 $921.10。

  • (a) 远期曲线定义: 指在某一特定时点上,将同一基础资产在不同连续未来交割月份的期货或远期价格绘制而成的函数曲线。
  • (b) 价格形态分析:
    • 该曲线严格单调递增 (FFeb<FApr<⋯<FDec) → 升水市场 (Contango)。
    • 对于黄金等纯投资性资产,曲线上升斜率主要反映了其持有成本 (Cost of Carry) (r+u),其中 r 为利率,u 为每年的仓储成本(占资产价值的百分比):即用于购买并持有黄金的融资利息成本加上金库仓储与保险费用。
    • 市场预期防范陷阱: 升水市场并不直接等同于市场预期未来即期价格一定会按此斜率上升。在现代资产定价理论中: F0=E(ST)e(r−k)T 其中 E(ST) 为 T 时刻现货价格的期望值,k 为投资者对基础资产要求的风险调整期望收益率。
Page 20 · Futures ContractsSlide ↗

Interpreting the Gold Forward Curve & Market Expectations

ETQ 2 Problem Setup: Gold futures on COMEX (2 Feb 2009): Feb $907.00, Apr $909.50, Jun $912.40, Aug $915.20, Oct $918.00, Dec $921.10.
  • (a) Definition of Forward Curve: The graphical representation plotting the prices of futures or forward contracts across consecutive future delivery dates observed at a single point in time.
  • (b) Pattern Analysis:
    • The curve is strictly upward-sloping (FFeb<FApr<⋯<FDec) → Contango.
    • For an investment asset like gold, the slope reflects the cost of carry (r+u), where r is the interest rate and u is the storage cost (% of asset value per year): interest rate to finance gold storage plus vault/insurance costs.
    • Market Expectations Caveat: Contango does not necessarily mean the market expects spot prices to rise by the full slope. In modern asset pricing: F0=E(ST)e(r−k)T where E(ST) is the expected spot price at T and k is the expected return demanded by investors.
第 21 页 · 期权导论幻灯片 ↗

期权合约导论

  • 期权是一种合约,赋予持有人在某一日期之前(美式)或在某一日期当天(欧式)(T),按某一价格 (K,期权的执行价;这里 K 不再是远期交割价) 买入/卖出基础资产的权利(而非义务)
    • 买方为获得这一权利,向卖方(立权人 Writer)支付期权费(权利金)
    • 欧式:仅能在到期日行权;美式:到期日及之前任何时间均可行权
  • 期权矩阵 (Options Matrix)
看涨期权 (Call)看跌期权 (Put)
买方(多头)买入的权利卖出的权利
卖方(空头,立权人)卖出的义务买入的义务
Page 21 · OptionsSlide ↗

Options

  • An option is a contract which confers a right (not an obligation) to buy/sell an underlying asset by (American) or at (European) a certain date (T) for a certain price (K, the option's strike price; here K is no longer the forward delivery price)
    • The buyer pays the seller (writer) a premium for this right
    • European: exercised only on the expiration date; American: at any time up to and including it
  • Options Matrix
CallPut
Buyer (long)Right to buyRight to sell
Writer (short)Obligation to sellObligation to buy
第 22 页 · 衍生品用途幻灯片 ↗

金融衍生品的核心用途

  • 套期保值 (Hedging)
    • 针对已经拥有或计划买卖的资产,防范价格发生不利变动;降低风险、锁定价格
  • 投机 (Speculation)
    • 根据对未来价格变动的判断在市场上建立头寸,从预期的价格变动中获利
    • 承担风险以期获利;杠杆放大收益
    • 投机为衍生品市场提供流动性
  • 套利 (Arbitrage)
    • 利用短期市场低效率获取无风险利润(同时建立相互对冲的头寸)
    • 消除市场价格差异
  • 改变负债的性质(例如互换)
  • 交易者类型
    • 套期保值者、投机者、套利者
    • 做市商、共同基金、对冲基金
Page 22 · Derivatives UsesSlide ↗

Uses of Derivatives

  • Hedging
    • Seek protection against unfavourable price changes in an asset already owned or planned to be bought/sold; reduce risk and lock in the price
  • Speculation
    • Take a position in the market by betting on future price movements to earn profits from expected price changes
    • Take risk in the hopes of profit; leverage magnifies returns
    • Speculation provides liquidity in derivatives markets
  • Arbitrage
    • Make risk-free profits by taking advantage of short-term market inefficiencies (simultaneous offsetting positions)
    • Eliminates market price discrepancies
  • To change the nature of a liability (e.g. swaps)
  • Types of traders
    • Hedgers, speculators, arbitrageurs
    • Market makers, mutual funds, hedge funds
第 23 页 · 套期保值幻灯片 ↗

案例分析 – 利用远期合约进行套期保值

  • 一家美国公司将在 3 个月后为从英国进口的商品支付 1,000 万英镑。3 个月期远期汇率为 1.6192。
  • 公司决定通过持有远期合约多头来套期保值
    • 锁定 1.6192 的汇率
    • 将 3 个月后支付的价款固定为 16,192,000 美元(10,000,000 × 1.6192)
  • 利用远期合约套期保值消除了不确定性;但不能保证套期保值的结果更好
    • 若 3 个月后的汇率 < 1.6192:不套期保值的结果更好
    • 若 3 个月后的汇率 > 1.6192:套期保值的结果更好
Page 23 · HedgingSlide ↗

Example – Hedging with Forwards

  • A US company will pay £10 million for imports from Britain in 3 months. The 3-month forward exchange rate is 1.6192.
  • The company decides to hedge by using a long position in a forward contract
    • To lock in an exchange rate of 1.6192
    • Fixes the price paid in 3 months to USD 16,192,000 (10,000,000 × 1.6192)
  • Hedging using forwards removes the uncertainty; there is no assurance that the outcome with hedging will be better
    • If exchange rate in 3 months < 1.6192: outcome without hedging is better
    • If exchange rate in 3 months > 1.6192: outcome with hedging is better
第 24 页 · 套期保值幻灯片 ↗

案例分析 – 利用期权进行套期保值

  • 某投资者持有 1,000 股微软股票,当前每股价值 28 美元。一份执行价格为 27.50 美元的 2 个月期看跌期权价格为 1 美元。
  • 投资者决定买入 10 张看跌期权合约(每张 100 股)进行套期保值。
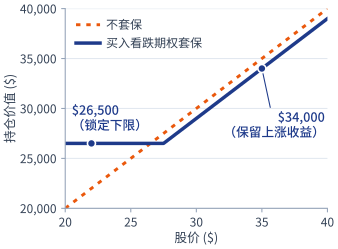
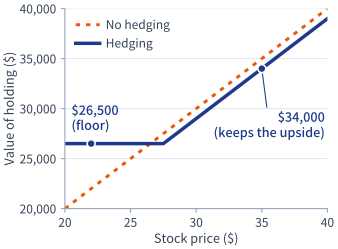
有无套期保值时持仓价值随股价变化的情况
  • 股价 $20:行使看跌期权,以 $27.50 卖出 1,000 股:$27,500 − $1,000 = $26,500
  • 股价 $35:看跌期权作废,在市场上卖出股票得 $35,000 − $1,000 = $34,000
Page 24 · HedgingSlide ↗

Example – Hedging with Options

  • An investor owns 1,000 Microsoft shares currently worth $28 per share. A two-month put with a strike price of $27.50 costs $1.
  • The investor decides to hedge by buying 10 put option contracts (100 shares each).
Value of the holding with and without hedging, as a function of the stock price
  • Stock price $20: exercise the puts, sell 1,000 shares at $27.50: $27,500 − $1,000 = $26,500
  • Stock price $35: puts expire worthless, sell the shares for $35,000 − $1,000 = $34,000
第 25 页 · 套期保值幻灯片 ↗

远期对冲与期权对冲对比

比较特征 远期合约 (Forwards) 期权合约 (Options)
前期成本 初始零现金支付 需立即支付期权费 (权利金)
对冲性质 锁定完全固定的未来价格/汇率 提供价格保险 (设定下限底线或上限顶线)
防范下行风险 是 (有效锁定风险) 是 (有效对冲不利变动)
分享上行收益 否 (上行潜在收益被完全消除) 是 (保留上涨收益,仅扣除期权费)
义务与权利 对交易双方均构成强制性约束 买方享有选择权利,卖方承担被动履约义务
Page 25 · HedgingSlide ↗

Hedging with Forwards and with Options

FeatureForwardsOptions
Upfront CostZero initial paymentOption premium paid immediately
Nature of HedgeLocks in a fixed price/rateProvides price insurance (a floor or ceiling)
Downside ProtectionYesYes
Upside ParticipationNo (eliminated)Yes (retained, minus premium paid)
Obligation vs RightBinding obligation on both partiesRight for buyer; obligation for writer
第 26 页 · 投机策略幻灯片 ↗

利用期货进行投机交易

  • 一位美国投机者认为英镑 (£) 将在未来 2 个月内升值,并愿意投机 250,000 英镑。
  • 有哪些可选策略?
    • 今天买入 250,000 英镑,存入生息账户,日后再卖出。
    • 持有英镑期货合约的多头头寸。
  • 两种策略的盈亏相同;区别在于
    • 买入英镑需要前期投资(例如即期汇率 1.4400 时需 360,000 美元)
    • 期货策略所需的前期投资较少(仅需保证金):以杠杆建立大额投机头寸(例如 4 张 CME 合约,每张 62,500 英镑,保证金每张 5,000 美元,共 20,000 美元)
Page 26 · SpeculationSlide ↗

Speculating with Futures

  • A US speculator believes that the £ will rise over the next 2 months and he is willing to speculate on £250,000.
  • What are the alternative strategies?
    • Buy £250,000 today, invest them in an interest-bearing account and sell it later.
    • Long position in futures contracts on £.
  • The profit/loss from both strategies is the same; the difference is that
    • Buying £ requires up-front investment (e.g. $360,000 at a spot rate of 1.4400)
    • The futures strategy requires less up-front investment (only margin): leverage to take a large speculative position (e.g. 4 CME contracts of £62,500 with $5,000 margin each = $20,000)
第 27 页 · 投机策略幻灯片 ↗

利用期权进行投机交易

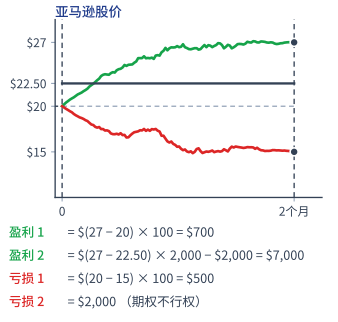
  • 某投资者有 2,000 美元可供投资,预期亚马逊 (Amazon.com) 的价值将在未来 2 个月内上升。当前股价为 20 美元,执行价格为 22.50 美元的 2 个月期看涨期权价格为 1 美元。有哪些可选策略?
    • 买入 100 股股票
    • 买入 20 张看涨期权合约(2,000 份看涨期权)
亚马逊股价 2 个月的两条价格路径:从 20 美元升至 27 美元或降至 15 美元,执行价 22.50 美元,以及买入 100 股(1)或 2,000 份看涨期权(2)的盈亏
Page 27 · SpeculationSlide ↗

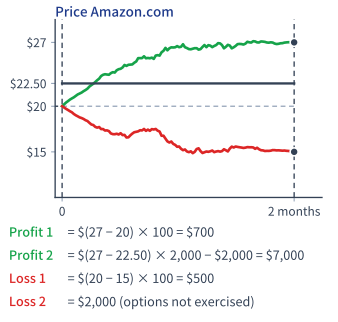
Speculating with Options

  • An investor with $2,000 to invest expects the value of Amazon.com to increase over the next 2 months. The current stock price is $20 and the price of a 2-month call option with a strike of $22.50 is $1. What are the alternative strategies?
    • Buy 100 shares
    • Long 20 call option contracts (2,000 call options)
Two-month price paths of Amazon.com from $20 up to $27 or down to $15, with the strike at $22.50, and the profits and losses of buying 100 shares (1) or 2,000 calls (2)
第 28 页 · 投机策略幻灯片 ↗

利用期权进行投机交易 – 2 个月后的结果

  • S0=$20;2 个月期、执行价格 K=$22.50 的看涨期权价格为 c=$1.00。投资预算 $2,000。
  • 策略 A:以 $2,000 买入 100 股股票。策略 B:以 $2,000 买入 2,000 份看涨期权(20 张合约)。
  • 2 个月后的不同情景:
    到期股票价格策略 A (买入 100 股股票)策略 B (买入 2,000 份看涨期权)
    下跌至 $15持仓市值 $1,500 (亏损:-$500 / -25%)期权价值 $0 (全额亏损:-$2,000 / -100%)
    上涨至 $27持仓市值 $2,700 (盈利:+$700 / +35%)期权价值 2,000×$4.50=$9,000 (盈利:+$7,000 / +350%)
Page 28 · SpeculationSlide ↗

Speculating with Options – Outcomes at 2 Months

  • S0=$20; 2-month call with strike K=$22.50 costs c=$1.00. Budget $2,000.
  • Strategy A: buy 100 shares for $2,000. Strategy B: buy 2,000 call options (20 contracts) for $2,000.
  • Outcome scenarios at 2 months:
    Terminal Stock PriceStrategy A (100 Shares)Strategy B (2,000 Calls)
    Drops to $15Value $1,500 (Loss: -$500 / -25%)Value $0 (Total Loss: -$2,000 / -100%)
    Rises to $27Value $2,700 (Gain: +$700 / +35%)Value 2,000×$4.50=$9,000 (Gain: +$7,000 / +350%)
第 29 页 · 投机策略幻灯片 ↗

期货投机与期权投机对比

  • 期货投机特征:
    • 前期资本投入极小(仅需缴纳履约保证金)。
    • 线性损益结构:潜在收益无上限,但潜在亏损同样无底线,且可能远远超过最初存入的保证金本金。
  • 期权投机特征:
    • 前期最大损失严格限定于已支付的期权费权利金。
    • 非线性损益结构:潜在收益无上限;下行亏损有限,最大仅为 100% 权利金;上行杠杆在股价大幅突破时可带来数倍爆发性回报(>300%)。
    • 但前提是股价必须大幅超越执行价格,足以抵消购买期权所支付的时间价值。
Page 29 · SpeculationSlide ↗

Speculating with Futures and with Options

  • Futures Speculation:
    • Small upfront investment (only margin deposit required).
    • Linear payoff: Potential gain is unlimited, but potential loss is also unlimited and can exceed initial margin.
  • Options Speculation:
    • Upfront cost is strictly limited to the option premium paid.
    • Non-linear payoff: Potential gain is unlimited, while downside loss is strictly capped at 100% of premium (limited loss); upside leverage can deliver explosive returns (>300%).
    • However, requires stock to move significantly beyond the strike price to overcome the time value paid.
第 30 页 · 投机策略幻灯片 ↗

股票与看涨期权收益平衡点分析

案例设定: ABC 有限公司股票当前价格 S0=$94。3 个月期、执行价 K=$95 的看涨期权价格 c=$4.70。总投资预算 = $9,400。

  • 策略 1:投入 $9,400 购买 100 股股票。
  • 策略 2:投入 $9,400 购买 2,000 份看涨期权(20 张合约,2,000×$4.70=$9,400)。

期权策略收益超越买入股票策略的盈亏平衡点股价:

期权策略净利润>股票策略净利润 2,000×max(ST−95,0)−9,400>100×(ST−94) 2,000(ST−95)−9,400=100(ST−94)⟹1,900ST=190,000⟹ST=$100.00
  • 若 ST≤$95.00:期权到期毫无价值作废(亏损 100% = -$9,400)。而股票仅损失 100×(94−ST)。
  • 若 $95.00<ST<$100.00:期权获得部分行权收益,但股票投资的收益率仍然更高。
  • 若 ST>$100.00:得益于 20:1 的高财务杠杆,看涨期权策略将带来远超股票的超额爆发性回报!
Page 30 · SpeculationSlide ↗

Stock vs. Call Option Profit Breakeven Analysis

ETQ 1 Setup: ABC Ltd stock price S0=$94. Three-month 95-call option K=$95, price c=$4.70. Budget = $9,400.

  • Strategy 1: Buy 100 shares for $9,400.
  • Strategy 2: Buy 2,000 call options (20 contracts) for 2,000×$4.70=$9,400.

Breakeven share price for Option Strategy to be more profitable:

ProfitOptions>ProfitShares 2,000×max(ST−95,0)−9,400>100×(ST−94) 2,000(ST−95)−9,400=100(ST−94)⟹1,900ST=190,000⟹ST=$100.00
  • If ST≤$95.00: Options expire worthless (100% loss = -$9,400). Shares lose only 100×(94−ST).
  • If $95.00<ST<$100.00: Options yield some payoff, but shares remain more profitable.
  • If ST>$100.00: Call options generate substantially higher profit due to 20:1 leverage!
第 31 页 · 套利机制幻灯片 ↗

案例分析 – 黄金期货套利 (期货价格被高估)

  • 假设:黄金现货价格 S=$1,390/盎司,1 年期年利率 r=5%(单利),黄金没有收益也没有仓储成本。
  • 市场上 1 年期黄金期货报价:Fmkt=$1,485。
  • 理论远期价格:Ftheor=$1,390×(1+0.05)=$1,459.50。
  • 由于 Fmkt>Ftheor,黄金期货价格被高估!是否存在套利机会?有:“现货-期货正向套利 (Cash-and-Carry)”。
    现在 (t=0)1 年后 (T=1)
    以 5% 年利率借入 $1,390,期限 1 年偿还贷款:$1,390×1.05=−$1,459.50
    以 $1,390 买入 1 盎司黄金按期货合约交付黄金
    以 $1,485 卖出(做空)1 年期黄金期货合约收取期货价格:+$1,485.00
    今日净现金流 = $0套利利润 = $(1,485 − 1,459.50) = 每盎司 $25.50
Page 31 · ArbitrageSlide ↗

Example – Gold Futures Arbitrage (Overpriced)

  • Assume: spot price of gold S=$1,390/oz, 1-year interest rate r=5% per annum (simple interest), no income or storage costs for gold.
  • Quoted 1-year futures price: Fmkt=$1,485.
  • Theoretical forward price: Ftheor=$1,390×(1+0.05)=$1,459.50.
  • Since Fmkt>Ftheor, gold futures are overpriced! Is there an arbitrage opportunity? Yes: “cash-and-carry” arbitrage.
    Now (t=0)After 1 year (T=1)
    Borrow $1,390 at 5% p.a. for 1 yearRepay the loan: $1,390×1.05=−$1,459.50
    Buy 1 oz of gold for $1,390Deliver the gold under the futures contract
    Short a 1-year gold futures contract at $1,485Receive the futures price: +$1,485.00
    Net cash flow today = $0Arbitrage profit = $(1,485 − 1,459.50) = $25.50 per oz
第 32 页 · 套利机制幻灯片 ↗

案例分析 – 黄金期货套利 (期货价格被低估)

  • 假设:S=$1,390/盎司,r=5%,黄金没有收益也没有仓储成本;Ftheor=$1,459.50。
  • 市场上 1 年期黄金期货报价:Fmkt=$1,390。
  • 由于 Fmkt<Ftheor,黄金期货价格被低估!是否存在套利机会?有:“反向现货-期货套利 (Reverse Cash-and-Carry)”。
    现在 (t=0)1 年后 (T=1)
    卖出(卖空)黄金,得到 $1,390按期货合约接受黄金交割
    将 $1,390 按 5% 年利率投资 1 年投资增长为:$1,390×1.05=+$1,459.50
    以 $1,390 买入 1 年期黄金期货合约(多头)支付期货价格:−$1,390.00
    今日净现金流 = $0套利利润 = $(1,459.50 − 1,390) = 每盎司 $69.50
Page 32 · ArbitrageSlide ↗

Example – Gold Futures Arbitrage (Underpriced)

  • Assume: S=$1,390/oz, r=5% per annum, no income or storage costs for gold; Ftheor=$1,459.50.
  • Quoted 1-year futures price: Fmkt=$1,390.
  • Since Fmkt<Ftheor, gold futures are underpriced! Is there an arbitrage opportunity? Yes: “reverse cash-and-carry” arbitrage.
    Now (t=0)After 1 year (T=1)
    Sell (short sell) gold for $1,390Take delivery of gold under the futures contract
    Invest $1,390 at 5% p.a. for 1 yearInvestment grows to $1,390×1.05=+$1,459.50
    Long a 1-year gold futures contract at $1,390Pay the futures price: −$1,390.00
    Net cash flow today = $0Arbitrage profit = $(1,459.50 − 1,390) = $69.50 per oz
第 33 页 · 套利机制幻灯片 ↗

黄金的理论期货价格

  • 期货价格应该是多少?
  • 若黄金现货价格为 S,一份 T 年后交割的期货合约的期货价格为 F,则
    F=S(1+r)T
    其中 r 为 1 年期(本币)单利利率。
  • 在我们的例子中,S=$1,390,T=1,r=0.05,因此 F=$1,390(1+0.05)=$1,459.50。
  • 若 F>S(1+r)T:套利者借款买入现货并做空期货(正向现货-期货套利 Cash-and-Carry)。
  • 若 F<S(1+r)T:套利者卖空现货、贷出所得资金并买入期货(反向现货-期货套利 Reverse Cash-and-Carry)。
  • 若采用连续复利(Hull 记号),同一关系写作 F0=S0erT。
Page 33 · ArbitrageSlide ↗

The Futures Price of Gold

  • What should the futures price be?
  • If the spot price of gold is S and the futures price for a contract deliverable in T years is F, then
    F=S(1+r)T
    where r is the 1-year (domestic currency) simple interest rate.
  • In our examples, S=$1,390, T=1 and r=0.05, so that F=$1,390(1+0.05)=$1,459.50.
  • If F>S(1+r)T: arbitrageurs borrow, buy spot, short futures (cash-and-carry).
  • If F<S(1+r)T: arbitrageurs short spot, lend the proceeds, buy futures (reverse cash-and-carry).
  • With continuous compounding (Hull's notation) the same relation reads F0=S0erT.
第 34 页 · 套利机制幻灯片 ↗

案例分析 – 原油期货套利 (消费性资产)

  • 参数设定: 原油即期现货价格 S=$85,利率 r=5% p.a.,年化仓储成本 u=2% p.a.。
  • 情景 1:1 年期期货市场报价 F=$93:
    • 持有成本决定的理论价格上限:Fmax=85×(1+0.05+0.02)=$90.95。
    • 由于 $93>$90.95,正向现货-期货套利完全可行(借款、买入原油、储存储备、做空期货 → 锁定确定性无风险利润)。
  • 情景 2:1 年期期货市场报价 F=$82:
    • 此时是否存在无风险套利机会?不存在!
    • 反向现货-期货套利不可行(原油是消费性资产,并非总能卖空):普通市场参与者极难在现货市场直接借入并卖空实物原油;而商业库存持有者由于需要维持生产运营的便利收益 (Convenience Yield),也不愿清空出售现货库存。
Page 34 · ArbitrageSlide ↗

Example – Oil Futures Arbitrage (Consumption Asset)

  • Setup: Spot oil S=$85, r=5% p.a., storage cost u=2% p.a.
  • Scenario 1: Quoted 1-year futures F=$93:
    • Cost of carry upper bound: Fmax=85×(1+0.05+0.02)=$90.95.
    • Since $93>$90.95, cash-and-carry arbitrage WORKS (borrow, buy oil, store, sell futures → guaranteed profit).
  • Scenario 2: Quoted 1-year futures F=$82:
    • Is there an arbitrage opportunity? NO!
    • Reverse cash-and-carry is not available: short-selling oil is not always possible because oil is a consumption asset – market participants cannot easily short sell physical crude oil, and commercial inventory holders will not sell stock due to operational convenience yield.