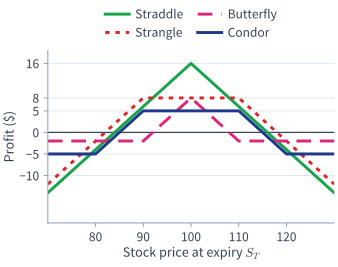
Long vs Short Straddles: Volatility Mechanics & Dual Breakevens
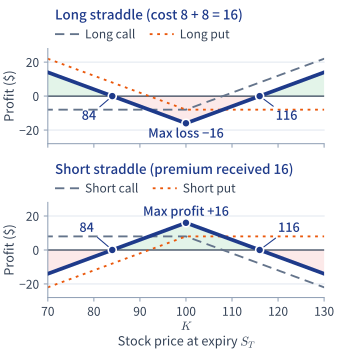
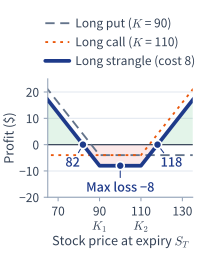
CME Definition: “Straddling the fence” — betting on both sides at once. A long straddle is the standard trade when a big breakout is expected but the direction is unknown (e.g. before earnings, regulatory approvals, or CPI data).
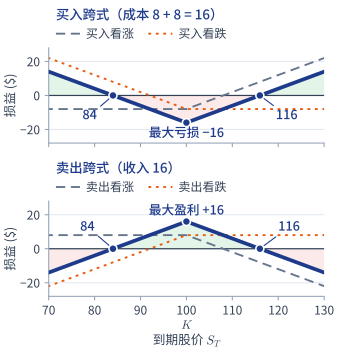
Long Straddle (Buy Call + Buy Put)
- Total Cost: (max loss at ).
- Upper Breakeven:
- Lower Breakeven:
- Greeks: Large positive Vega () and Gamma (); negative Theta () time decay.
Short Straddle (Sell Call + Sell Put)
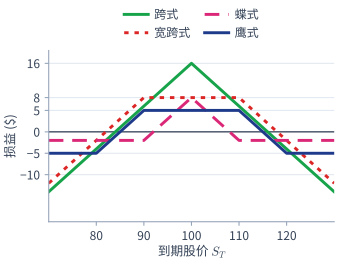
- Max Profit: (if the market closes exactly at ).
- Breakevens: Identical ().
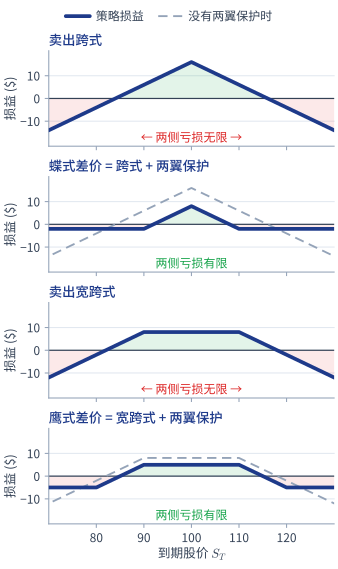
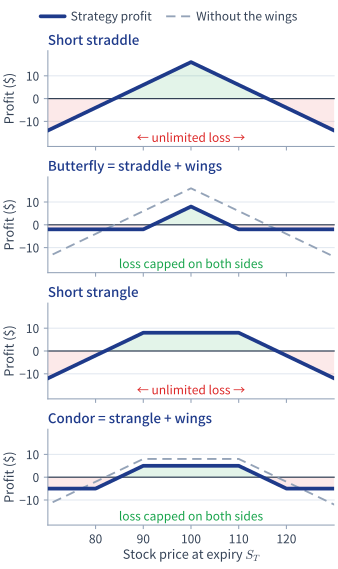
- Risk Profile: Unlimited loss if the stock jumps through either breakeven.
- Greeks: Positive Theta (, earns decay), negative Vega ().
Simple Example: , call and put $8 each, so . Breakevens: and — profit starts only above $116 or below $84; at exactly $100 the full $16 is lost.